
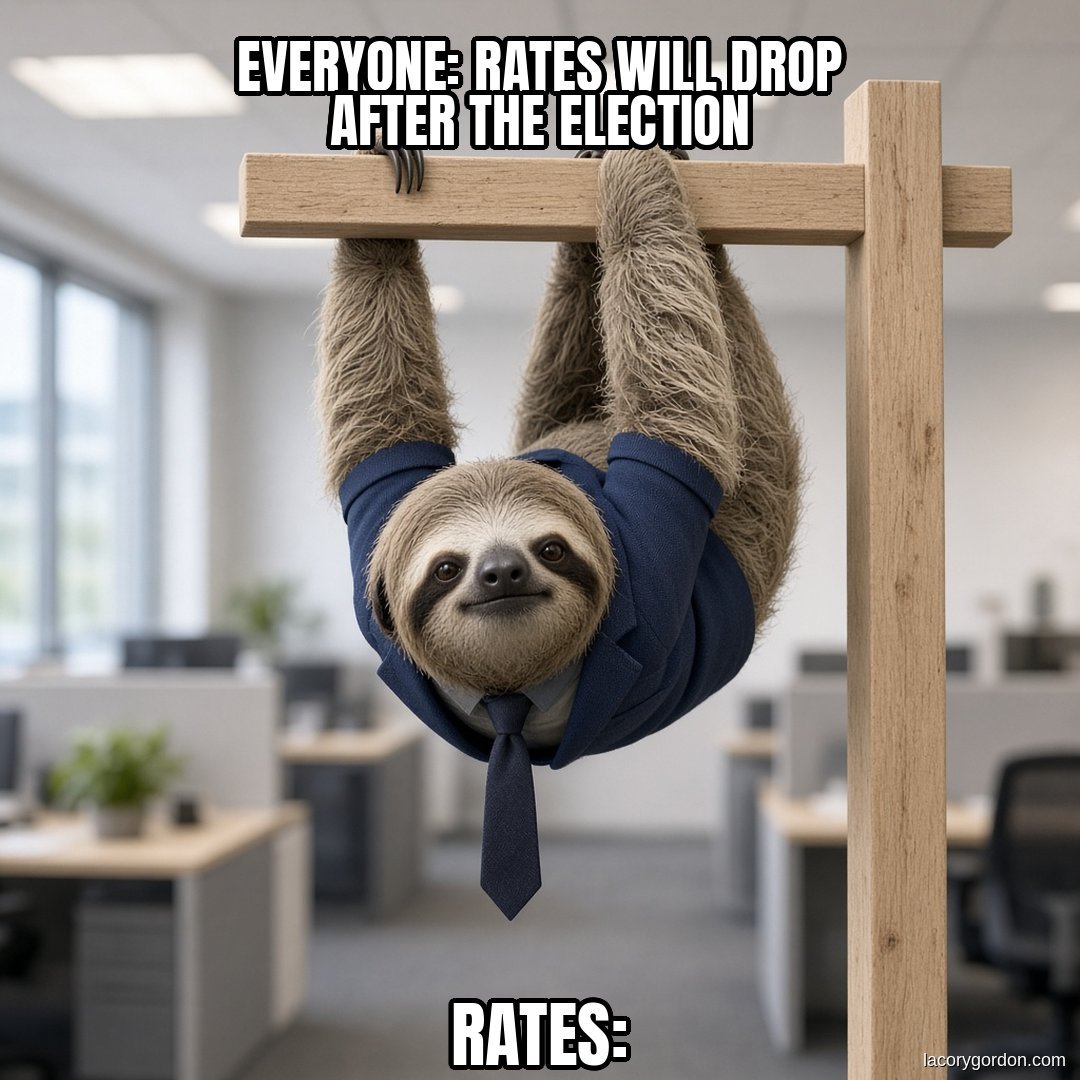
Election Night turns into Rate Night in every group chat. After the Nov. 3 midterms, half the room swore rates would crash and the other half swore they would spike. Freddie Mac still printed 7.18%. Here is what actually moved, and what Omaha buyers should watch next.
I am Lacory Gordon, a REALTOR with Revel Realty in Bellevue, serving Omaha, Papillion, La Vista, and the rest of the metro. Every other year, Election Night turns into Rate Night in group chats. This week was no different.
On Nov. 3, 2026, Democrats won majorities in both the U.S. House and Senate. That is real. AP, Ballotpedia, Reuters, and The Guardian all reported the same story: a clear flip of Congress. Around here, people also watched Douglas County races the same way they watch Husker scores. Loud. Opinions everywhere. Almost none of them about your actual payment.
Then the questions started.
“So rates crash now, right?”
“Or do they spike?”
“Should I buy before January?”
“Should I wait until 2028?”
Here is the comedy part. Half the room swears the other party’s win means cheaper houses. The other half swears the opposite. Both sides speak with the confidence of someone who just unlocked a finance degree in a comment thread. Neither side gets to set the 10-year Treasury yield.
Key takeaways
- Democrats took the House and Senate in the Nov. 3, 2026 midterms. That is confirmed by major outlets. It is not a rate lock.
- Freddie Mac’s Nov. 5 survey put the 30-year fixed average at 7.18%, down slightly from 7.24% the prior week. The 15-year averaged 6.57%.
- The 10-year Treasury eased after the election. Mortgage rates followed a little. That can reverse.
- The Fed’s next rate decision is after the Dec. 8 to 9 meeting. Congress does not cast that vote.
- Omaha buyers should use a current lender quote and a payment ceiling, not a group chat prediction.
What actually moved after the vote
Mortgage rates do not wake up, read the popular vote, and pick a number. They mostly follow bond markets, especially the 10-year Treasury and mortgage-backed securities.
After the midterms, yields eased. Reporting around Nov. 3 to Nov. 5 put the 10-year Treasury near the mid 4.8% range after sitting closer to the mid to high 4.9%s right around Election Day. Freddie Mac’s Primary Mortgage Market Survey for the week ending Nov. 5 put the average 30-year fixed at 7.18%, down from 7.24% the week before. The 15-year averaged 6.57%. That was the third straight weekly dip.
So yes, rates nudged lower in the same window. No, that is not a promise they keep falling because one party controls Congress. Markets were also reacting to oil prices, tech stock jitters, and what a split Washington might mean for big spending. Those stories change weekly.
The Fed still has a calendar
This part gets skipped in memes. The Federal Reserve is not Congress.
At the Oct. 27 to 28 meeting, the Fed held the federal funds target range at 3.75% to 4.00%. The next decision is due after the Dec. 8 to 9 meeting. Mortgage rates can move before that meeting, after it, or in spite of it. Anyone telling you “the midterms lock in your rate for 2027” is selling certainty they do not own.
What this means if you are buying in Omaha
If you are shopping Bellevue, Papillion, west Omaha, or La Vista right now, treat election week like weather. Notice it. Do not build your whole plan around one forecast.
A few practical moves that still work after any election: get a real preapproval, ask your lender for a same-day quote on the house you actually want, and know your ceiling payment before you fall in love with a listing. Freddie Mac is a weekly average. Your lock is personal. A quarter point either way matters less than buying a house you can sleep in.
I am not here to cheer a party. I am here to keep you from making a six-figure decision based on a Tuesday night graphic. Nobody can promise rates will rise or fall after an election. History is full of both. What you can control is your budget, your lender paperwork, and whether you are reacting to headlines or to a number on a Loan Estimate.
FAQ
Did the midterms lower mortgage rates?
They lined up with a small dip. Freddie Mac reported 7.18% for the 30-year as of Nov. 5, 2026, after 7.24% the week before. Markets also moved on oil, stocks, and deficit expectations. Correlation is not a guarantee of the next move.
Will rates fall more now that one party controls Congress?
Nobody knows. Some traders bet divided or opposition Congress slows spending and cools yields. Others wait for inflation data and the December Fed meeting. Honest answer: unpredictable.
Should Omaha buyers wait until after the December Fed meeting?
Only if waiting fits your life, not because a meme said so. If you found the right house and the payment works today, a calendar date is a weak reason to pause. If you are stretching already, wait for numbers that fit, not for politics.
General information only, not lending, legal, or tax advice. Rate figures change weekly. Your lender sets your actual quote and lock. Checked Nov. 9, 2026.
Sources
- AP News: Democrats win House and Senate, Nov. 2026 midterms
- Ballotpedia / Reuters / The Guardian: midterm seat counts (House and Senate majorities for Democrats)
- Freddie Mac PMMS: 30-year 7.18%, 15-year 6.57% as of Nov. 5, 2026
- CNBC / National Mortgage News: post-midterm Treasury yield move (10-year near mid-4.8%s)
- Federal Reserve FOMC calendar: held Oct. 27 to 28; next meeting Dec. 8 to 9, 2026; funds rate held at 3.75% to 4.00%
Group chat turned into a rate seminar?
If you want a second opinion that is local, call or text 402-297-6625 or email lacoryg@revelne.com. We can look at real quotes for Bellevue, Omaha, and Sarpy County without the cable news soundtrack. You can also use my contact page.
Lacory Gordon, REALTOR
Revel Realty
1313 Harlan Dr, Bellevue, NE 68005
